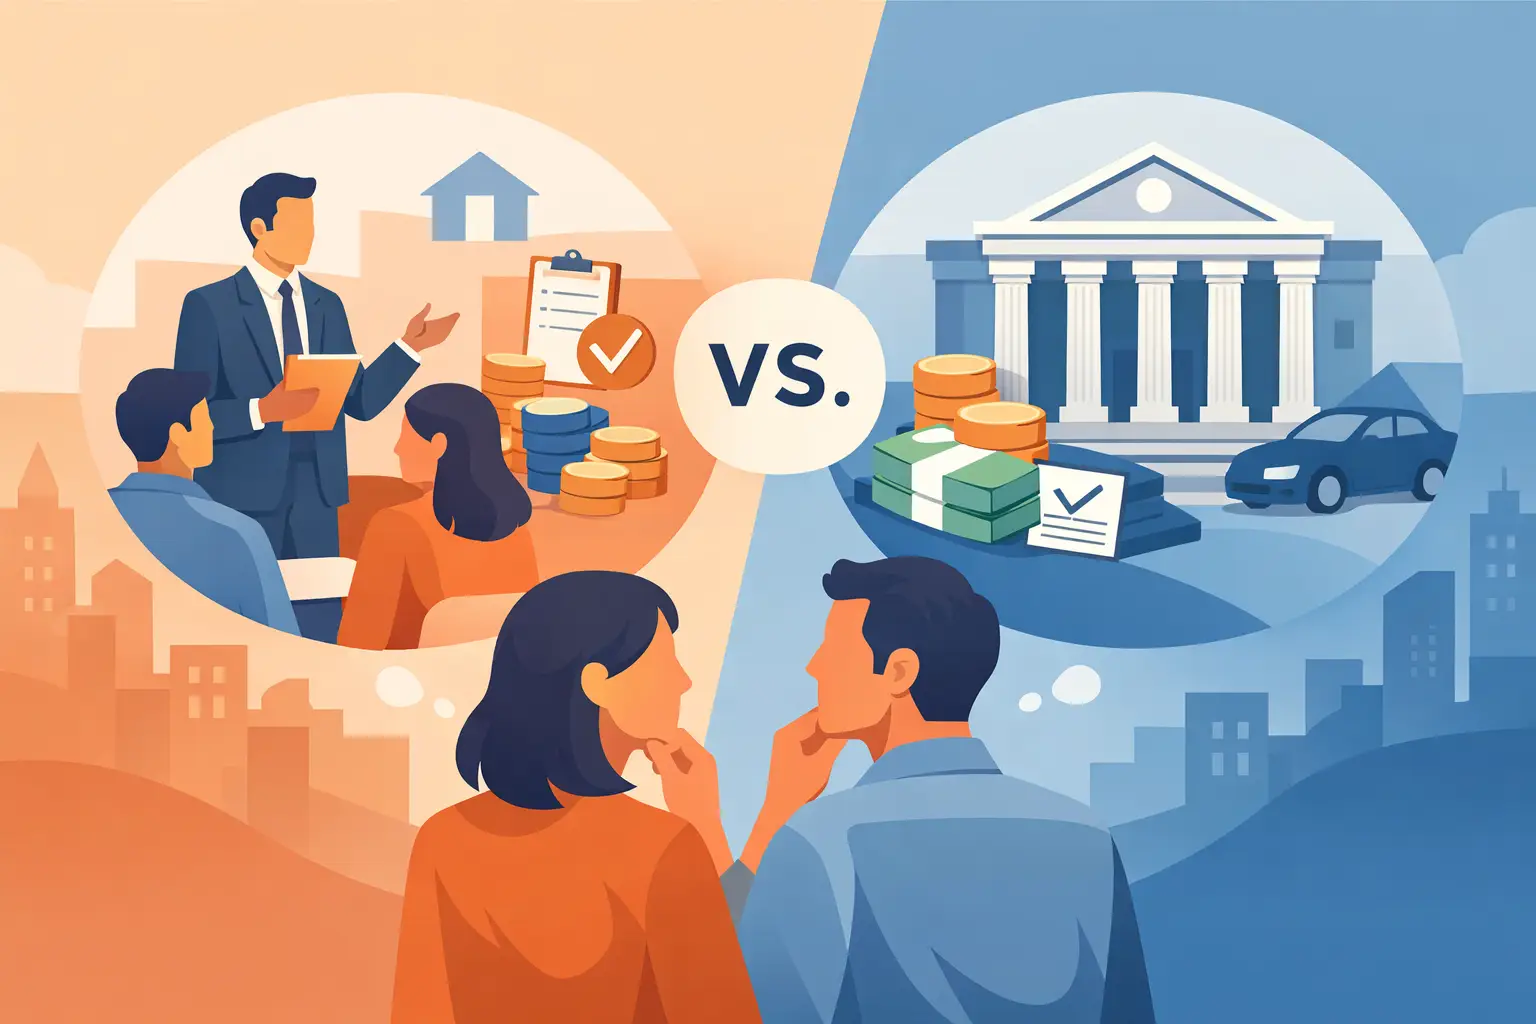
If you need finance for a car, ute, truck, trailer, equipment or business purchase, the choice often comes down to loan broker vs bank loan. On paper, both can get you funded. In practice, the experience can be very different, especially if you are self-employed, short on time, or trying to compare options without chasing half a dozen lenders yourself.
For many Australian borrowers, the real question is not which option is better in every case. It is which one is more likely to get the right result for your situation, with less back and forth and fewer delays.
Loan broker vs bank loan: what is the difference?
A bank lends its own money and offers its own products. If you apply directly with a bank, you are being assessed against that bank’s credit policy, product range and appetite for your type of deal.
A broker works differently. A finance broker looks at your needs, then compares suitable options across a panel of lenders. That matters because not every lender treats the same borrower, asset type or business profile the same way. One lender may be comfortable with a newer business buying a work ute. Another may be stronger on heavy vehicles, yellow goods or commercial equipment. Another may be more competitive on straightforward consumer car finance.
That broader view is often the biggest difference in the loan broker vs bank loan discussion. A bank gives you one set of options. A broker can usually show you more than one path.
When a bank loan makes sense
There are times when going directly to a bank is perfectly reasonable. If you already have a strong relationship with your bank, your income is easy to verify, your credit profile is clean, and your deal is simple, a bank may offer a suitable solution without much trouble.
This can work well for salaried borrowers with straightforward needs, or established businesses with strong financials and long banking history. Some clients also prefer keeping everything under one roof if their bank already handles transaction accounts and business banking.
Banks can also suit borrowers who are happy to do the legwork themselves. If you are comfortable comparing terms, following up on paperwork and negotiating directly, that process may feel manageable.
The trade-off is that you are still limited to one lender’s policy. If that bank says no, or offers terms that do not quite fit, you are back to square one.
When a loan broker may be the better fit
A broker tends to add the most value when the deal is not completely vanilla, or when speed matters.
That includes self-employed borrowers, tradies buying utes or equipment, transport operators adding trucks or trailers, and businesses looking for working capital or asset finance while trying to keep operations moving. In these cases, lender choice matters because policy differences matter.
A broker can also save time. Instead of making separate applications with multiple lenders, you usually provide your information once, then the broker works through the options for you. That does not remove paperwork entirely, but it can cut down the runaround.
This is where personalised support becomes more than a nice extra. A good broker helps package the application properly, explains what documents are needed, flags potential issues early and keeps the process moving from application through to settlement.
Speed is not just about approval time
Many borrowers compare broker and bank options based on interest rate alone. That matters, but it is not the whole picture. Speed matters too, especially when the asset is needed for work or the seller wants a quick turnaround.
A direct bank application can be fast when the deal fits neatly within policy and all documents are available upfront. But banks can also be slower when the application falls outside the standard box or needs human assessment.
A broker’s value on speed comes from knowing which lenders are likely to suit the deal before the application goes in. That can reduce wasted time with lenders that were unlikely to approve it in the first place. For a business owner trying to secure a replacement truck, a new excavator or additional working capital, that time saving can be significant.
Comparing rates, fees and overall value
A common assumption is that going direct to a bank always means the cheapest deal. Sometimes it does. Sometimes it does not.
The better question is what overall value looks like for your situation. Rate is part of it, but so are fees, loan term, repayment flexibility, balloon options where appropriate, approval speed and how well the structure matches the asset or business need.
For example, a slightly sharper rate is not much use if the lender moves too slowly and you lose the vehicle or equipment you needed. Likewise, a loan that looks cheap upfront may be less suitable if it comes with terms that do not work for your cash flow.
In a loan broker vs bank loan comparison, brokers can be useful because they compare multiple offers side by side. That makes it easier to judge the full picture rather than focusing on one headline number.
Self-employed and business borrowers often have more moving parts
This is one of the biggest areas where the choice matters.
If you are self-employed or running a business, your income may not fit the neat format a major bank prefers. You may have seasonal cash flow, recent ABN history, trust structures, asset-backed opportunities or urgent operational needs. None of that means finance is out of reach, but it can mean the right lender is not always the first one you think of.
A broker who understands business and commercial lending can often identify lenders that are more comfortable with your industry, trading history or asset type. That is particularly relevant for transport, construction, civil, mining support, agriculture and trade-based businesses where vehicles and equipment are income-producing assets, not lifestyle purchases.
A bank may still be an option. It is just not always the most flexible one.
Service matters more than most people expect
Finance can look simple until something needs clarifying. A valuation takes longer than expected. A document is missing. A lender wants more information about the asset or the business. That is where service becomes a real part of the result.
With a bank, you may be dealing with a branch contact, a call centre, or a lending team that handles a broad range of products. Some experiences are excellent. Others can feel slow or fragmented.
With a broker, the service tends to be more hands-on. You generally have one point of contact who understands the deal and keeps you updated. For borrowers who do not want to spend their week chasing lenders, that support can remove a lot of friction.
That is one reason many Australian borrowers use brokers for vehicle, equipment and business finance. It is not just about finding a lender. It is about getting the deal done without unnecessary complexity.
So, should you choose a loan broker or a bank loan?
It depends on what you value most.
If your deal is straightforward, you have time to shop around, and your bank is offering a competitive product that fits your needs, going direct may work just fine.
If you want choice, guidance and a simpler process, a broker often makes more sense. The same applies if you are self-employed, buying a specialised asset, or trying to move quickly without applying to multiple lenders one by one.
Neither option is automatically right for everyone. The best choice usually comes down to complexity, urgency and how much support you want during the process.
For borrowers who want finance without the headaches, having someone compare lenders, explain the options in plain English and manage the process can make a real difference. That is why many businesses and consumers across Australia choose to work with a brokerage like Rivercity Finance when time, clarity and flexibility matter.
Before you apply anywhere, be clear on the asset you are buying, how fast you need approval, what repayments your cash flow can comfortably handle, and whether you want to do the comparison work yourself. Once you know that, the right path tends to become a lot clearer.